What changed for 2025
The baseline conforming loan limit for a one-unit home rose to $806,500 nationwide. In designated high-cost areas, the ceiling is $1,209,750. FHFA.gov
In practice, loans at or below your county’s conforming limit can be bought by Fannie Mae/Freddie Mac; loans above that amount are jumbo (non-conforming). AP News
Where the line is locally
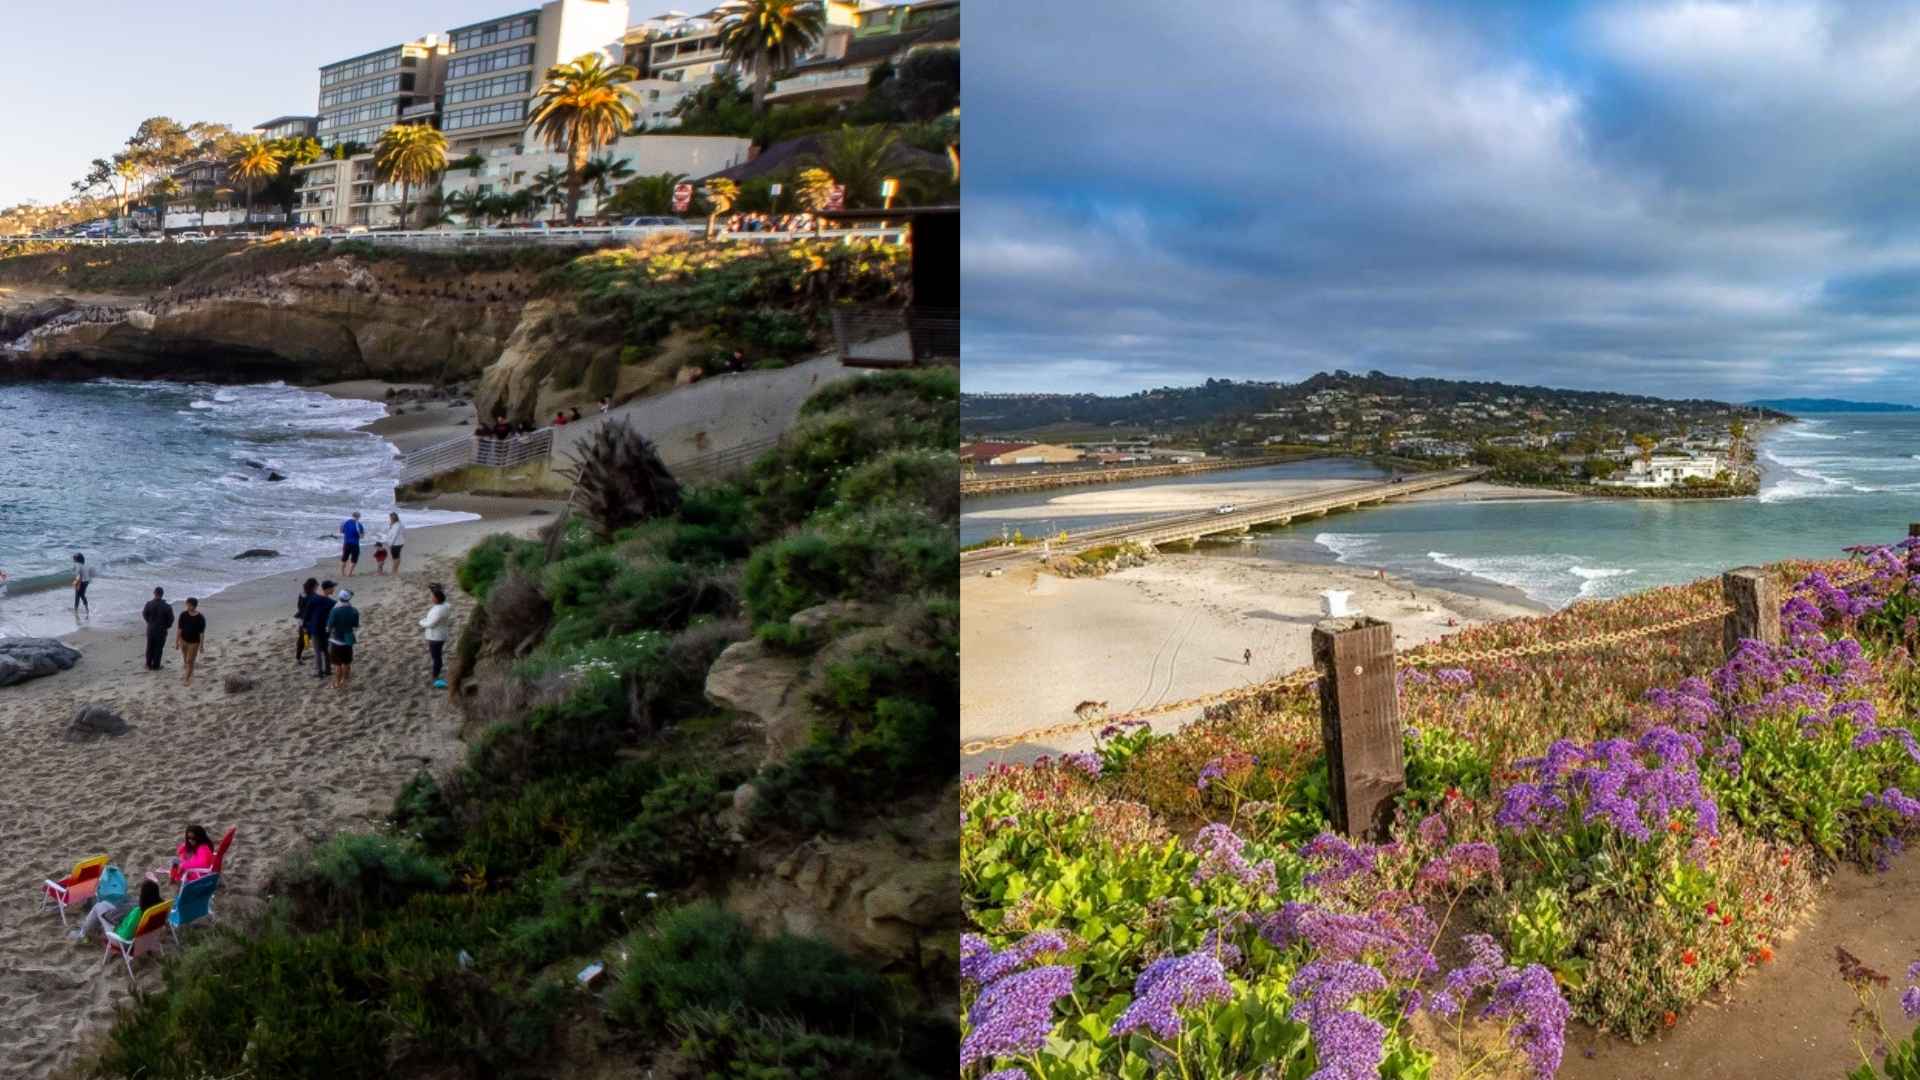
- San Diego County (1-unit): $1,077,550 (high-balance conforming). Above this is jumbo. FHFA.gov
- Riverside County (1-unit): $806,500 (baseline conforming). Above this is jumbo. FHFA.gov
Why the line matters
- Eligibility & pricing: Conforming loans follow standardized rules and can carry different pricing than jumbo. Depending on market conditions, jumbo may price higher, similar, or occasionally lower—you won’t know without quotes at both sizes.
- Underwriting: Jumbo loans often require higher credit scores, larger reserves, and lower DTI; conforming tolerances can be more flexible via automated underwriting. (Guideline differences vary by lender.)
- Appraisals & comps: Pricing homes just below/above the line can change the buyer pool—especially around thresholds like ~$800k–$850k in Riverside and ~$1.05M–$1.1M in San Diego.
Buyer strategy (San Diego & Riverside)
- Price-band planning: Ask your lender for dual scenarios—one just under the conforming cap and one just over—to see payment, rate, and cash-to-close differences.
- Aim for clean approvals: For jumbo, shore up reserves, minimize consumer debt, and document assets early. For conforming high-balance in San Diego, confirm AUS findings and any LLPA impacts.
- Structure offers smartly: If you’re near the line, consider rate-buydowns or seller credits to keep payments competitive.
- Refi window: If rates ease, note that jumbo→conforming refinances may open once balances drop (via paydown or appreciation). Keep records for recast or refi options.
Seller strategy
- Threshold pricing: If comps support it, listing just under the conforming cap can widen the buyer pool; if your home competes above the line, highlight features that justify jumbo financing (condition, location, ADU income, views).
- Appraisal file: Provide upgrades lists, permits, and rent potential (if applicable) to help the value case—especially for properties priced just over the conforming limit.
- Concessions as a lever: Strategically offer credits toward rate buydowns or closing costs to keep payments inside buyers’ target bands.
Quick reference (1-unit, 2025)
- Baseline conforming limit (U.S.): $806,500; high-cost ceiling: $1,209,750. FHFA.gov
- San Diego County: $1,077,550 (conforming); > $1,077,550 = jumbo. FHFA.gov
- Riverside County: $806,500 (conforming); > $806,500 = jumbo. FHFA.gov
This article is informational and not legal, tax, or lending advice. Always confirm program details with your lender; pricing and guidelines change.