Why this matters now
California’s homeowners’ insurance market is in flux. Regulators are rolling out a Sustainable Insurance Strategy that changes how wildfire risk is modeled and aims to expand coverage in harder-to-insure areas. The California FAIR Plan (insurer of last resort) is also evolving. For buyers and sellers in San Diego County and Riverside County, insurance can no longer be a last-minute checkbox—it’s a workstream with its own critical path during escrow.
The 2025 landscape—quick briefing
- Carriers & non-renewals: Some major carriers paused or reduced new business and executed non-renewals in certain zip codes.
- Rates & models: Forward-looking catastrophe models and reinsurance pass-throughs mean more location-sensitive pricing.
- FAIR Plan basics: FAIR Plan is a named-peril policy (primarily fire/smoke) that often requires a DIC “wrap” (Difference-in-Conditions) to add liability, water, theft—together approximating HO-3 for lenders. Residential limits are higher than in past years.
- Smoke claims scrutiny: Oversight actions and guidance continue; pay attention to smoke-damage handling and documentation.
Local reality: inland vs. coastal
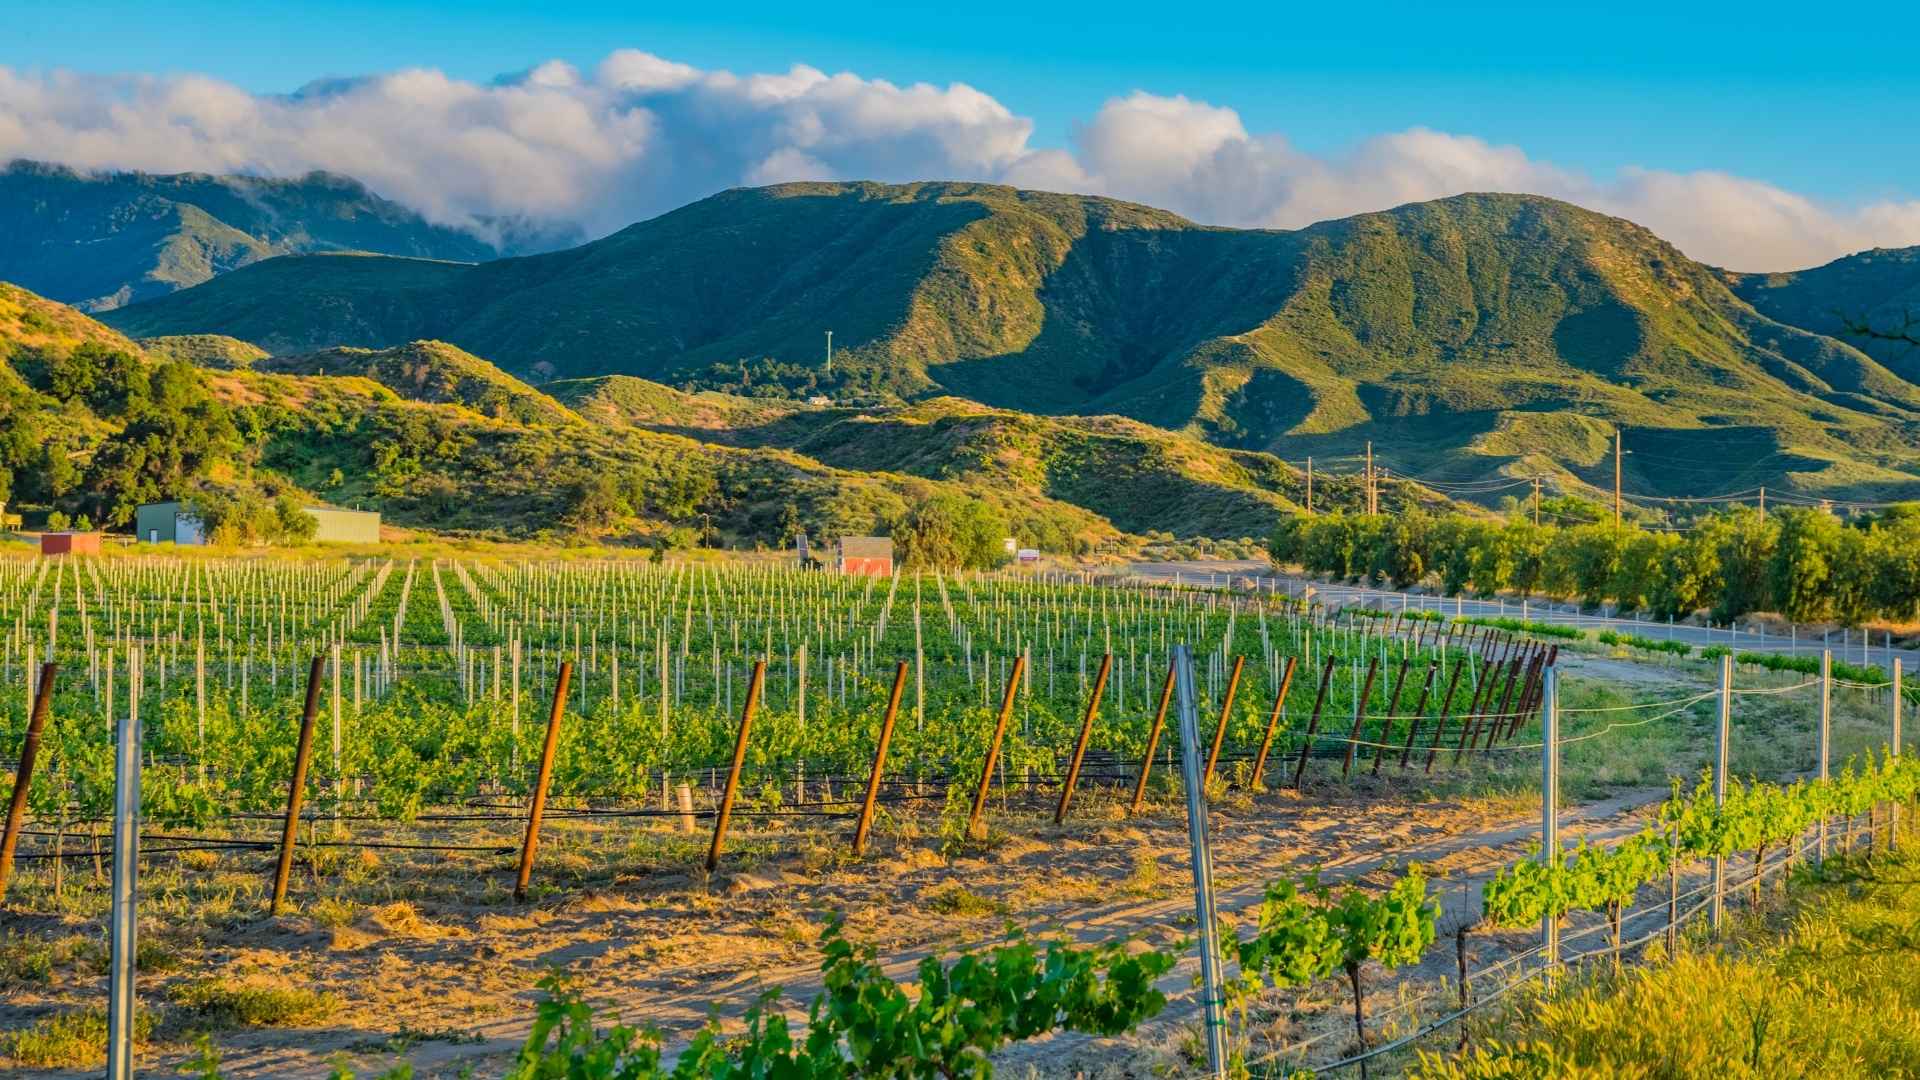
- Inland valleys (Temecula, Murrieta, Menifee, Fallbrook, Escondido): More parcels near or within High/Very High Fire Hazard Severity Zones. Quotes can vary widely and take longer.
- Coastal zones (Carlsbad, Encinitas, Oceanside): Generally easier placement, but pricing still reflects modeled risk and mitigation.
Use CAL FIRE’s FHSZ map viewer early in the search to understand baseline risk.
Buyer playbook: keep your escrow on track
- Start insurance the day you tour a home. Ask for standard-market quotes; if declined, get FAIR Plan + DIC quoted immediately.
- Add an “insurability” checkpoint to your offer timeline. Target a specific date to secure bindable terms well before loan docs.
- Verify replacement cost and sublimits. Check Coverage A (rebuild cost) and items like ordinance/law, other structures, and Additional Living Expense (ALE).
- Document mitigation for better pricing. Show proof of Safer from Wildfires steps and any Firewise community status.
- Bind early—don’t wait for CD signing. Lenders require evidence of insurance before funding; reduce last-minute underwriting questions.
- If you’re non-renewed post-closing, know your protections. In some cases (after declared wildfires), one-year moratoriums on non-renewals may apply.
Seller playbook: reduce surprises and protect your net
- Pre-list insurance check. Shop your renewal, gather a loss history if available, and compile mitigation proof (roof class, ember-resistant vents, Zone 0 photos).
- Disclose the insurance story. If you carry FAIR Plan + DIC, say so early so buyers plan realistic timelines and offers.
- Invest in visible hardening. Cleared 0–5 ft “Zone 0,” gutter guards, ember-resistant vents, and Class-A roofs can improve insurability and buyer confidence.
FAIR Plan + DIC, decoded (for escrows)
When private carriers won’t write the risk, a common solution is pairing a FAIR Plan fire/smoke policy with a DIC policy that adds liability and non-named perils. Lenders often accept this pairing as a functional HO-3 equivalent. For higher-value properties, brokers may add excess or surplus-lines coverage to close any gap.
What discounts are realistic?
Insurers in California must recognize certain mitigation steps under Safer from Wildfires and acknowledge Firewise USA communities. Actual savings vary by insurer and property, but good documentation—photos, receipts, contractor notes—helps both pricing and underwriting.
The 2025 regulatory glidepath (plain English)
- Catastrophe models: Allowing forward-looking wildfire models should gradually expand availability, though premiums may re-tier.
- Coverage obligations: Insurers operating in the state are expected to increase writing in wildfire-prone areas over time to help depopulate the FAIR Plan.
- FAIR Plan oversight: Expect continued operational adjustments, higher limits than before, and close attention to smoke-damage handling.
Your 10-point escrow checklist (print this)
- Run the address in the FHSZ map viewer.
- Request standard quotes and, if declined, FAIR Plan + DIC the same day.
- Confirm Coverage A (rebuild cost), ALE, and sublimits.
- Provide mitigation proof (Safer from Wildfires steps, Firewise).
- Confirm lender acceptability (FAIR Plan + DIC, mortgagee clause).
- Calendar a bind-by date at least a week before docs.
- Send evidence of insurance to the lender early.
- If non-renewed near closing, check for one-year moratorium eligibility.
- Save all quotes and underwriting emails for your file.
- After closing, schedule hardening upgrades within 30–60 days, then re-shop.
This article is informational and not legal, tax, or insurance advice. Always consult your carrier, broker, and lender.